By Water Source Type (Municipal Used Water, Industrial Wastewater, Stormwater & Rainwater, Other Water Sources), By Offering (Water Recovery Systems Equipment & System, Engineering, Procurement & Cons... ... , Procurement & Construction (EPC) Services, Operations & Maintenance (O&M) Services, Digital Monitoring & Automation Solutions), By Technology (Membrane-Based Water Recovery Systems, Membrane Bioreactor (MBR) Systems, Biological Water Recovery Systems, Advanced Treatment & Disinfection Systems, Adsorption & Ion Exchange Systems, Conventional & Physical-Chemical Treatment Systems, Others), By System Type (Centralized Water Reuse Systems, Decentralized Water Reuse Systems), By End User (Municipal Utilities, Industrial (Semiconductor & Electronics, Pharmaceuticals & Life Sciences, Food & Beverage, Chemicals & Petrochemicals, Power Generation, Other Manufacturing Industries), Commercial Buildings, Residential Developments, Hospitality & Healthcare, Government & Public Infrastructure), and others Read more
- Environment
- Sep 2026
- 135
- PDF, Excel, PPT
Taiwan Water Recovery Systems Market Key Takeaways
- The Taiwan water recovery systems market is valued at USD 0.58 billion in 2025 and is projected to reach USD 1.20 billion by 2032.
- The industry is projected to witness steady growth at an 11.05% CAGR.
- By membrane technology, membrane-based water recovery systems account for approximately a 42% share.
- By offering, the water recovery equipment & systems hold the leading position with a 55% share.
- The market is moderately consolidated, with the top five players accounting for approximately 40% combined share.
Taiwan Water Recovery Systems Market Size and Outlook
The water recovery systems market in Taiwan is valued at USD 0.58 billion in 2025 and is expected to reach USD 0.64 billion in 2026 and USD 1.20 billion by 2032, representing an 11.05% CAGR. The market is primarily shaped by industrial water-reuse requirements, with semiconductor and electronics manufacturing representing the most important demand base.
Industrial users represent the core demand pool. Taiwan’s science parks achieved an overall 74% industrial water recycling rate in 2024, while semiconductor and optoelectronics manufacturers achieved more than 85% process-water recycling. This indicates that water recovery is already integrated into industrial production rather than being limited to standalone wastewater treatment.
Semiconductor & electronics form the leading industrial application. Major manufacturing clusters in Hsinchu, Tainan, and Kaohsiung require large-scale water-recovery infrastructure. TSMC’s reclaimed-water projects illustrate this demand, including facilities planned around 36,000 m³/day in Southern Taiwan and 10,000 m³/day in Hsinchu.
Municipal utilities and government infrastructure provide another important demand channel for water recovery systems. Taiwan is increasingly converting municipal wastewater into reclaimed water for industrial use. In Tainan, a recycling facility supplies 23,090 tonnes/day of reclaimed water to semiconductor manufacturing, connecting municipal treatment infrastructure directly with industrial demand.
By 2032, industrial applications remain the primary demand base, led by semiconductor and electronics manufacturing, while municipal reclaimed-water infrastructure adds to overall system demand.
Taiwan Water Recovery Systems Market Key Indicators
- Taiwan requires development projects with planned water demand of 20,000 CMD or more to source at least 50% of industrial water from reclaimed-water systems. Separately, semiconductor and optoelectronics manufacturers in science parks achieved process-water recycling rates above 85% in 2024. Over five years, these requirements and high recycling benchmarks reinforce demand for onsite recovery systems in Hsinchu, Tainan, and Taichung.
- Taiwan is expanding reclaimed-water infrastructure to reduce pressure on conventional water sources amid climate-related supply risks and rising industrial demand. The WRA targets 1.32 million CMD of reclaimed-water supply by 2031, strengthening investment in recovery plants, pipelines, treatment systems, and monitoring infrastructure across major industrial clusters.
- Development projects with planned water demand of 20,000 CMD or more must source at least 50% of industrial water from reclaimed-water systems. Over five years, this requirement increases compliance-driven demand for reclaimed-water infrastructure among large industrial developments, particularly across Hsinchu, Tainan, Taichung, and Kaohsiung.
- Taiwan targets 1.32 million CMD of reclaimed-water supply by 2031. Over five years, this target creates a defined infrastructure pipeline spanning reclamation plants, treatment equipment, transmission systems, monitoring, and O&M services. Projects in Tainan, Taoyuan, Taichung, and other industrial regions strengthen procurement visibility for water recovery system suppliers.
Taiwan Water Recovery Systems Market Scope
| Category | Segments |
|---|---|
| By Water Source Type | (Municipal Used Water, Industrial Wastewater, Stormwater & Rainwater, Other Water Sources), |
| By Offering | (Water Recovery Systems Equipment & System, Engineering, Procurement & Construction (EPC) Services, Operations & Maintenance (O&M) Services, Digital Monitoring & Automation Solutions), |
| By Technology | (Membrane-Based Water Recovery Systems, Membrane Bioreactor (MBR) Systems, Biological Water Recovery Systems, Advanced Treatment & Disinfection Systems, Adsorption & Ion Exchange Systems, Conventional & Physical-Chemical Treatment Systems, Others), |
| By System Type | (Centralized Water Reuse Systems, Decentralized Water Reuse Systems), |
| By End User | (Municipal Utilities, Industrial (Semiconductor & Electronics, Pharmaceuticals & Life Sciences, Food & Beverage, Chemicals & Petrochemicals, Power Generation, Other Manufacturing Industries), Commercial Buildings, Residential Developments, Hospitality & Healthcare, Government & Public Infrastructure), |
Taiwan Water Recovery Systems Market Growth Drivers
Recurring Typhoon-Driven Drought Cycles Forcing Structural Investment in Water Recovery Systems
Taiwan’s dependence on typhoon-driven rainfall creates recurring water-supply pressure for semiconductor and other water-intensive industries. A 2024 study documented a decline in tropical-cyclone-induced rainfall since 2016, increasing the risk of spring-season water scarcity. This vulnerability became visible in recent years, when several reservoirs fell below 25% capacity, while major Hsinchu Science Park water users, including TSMC, reduced consumption by 5% ahead of the dry season.
Repeated drought exposure is shifting industrial water management from short-term conservation toward permanent water-recovery infrastructure. Taiwan has expanded technology-based water production and reclamation projects, while semiconductor manufacturers are increasing internal recovery rates to reduce dependence on conventional freshwater sources. TSMC, for example, increased its internal water recovery rate from 75% toward an 85% target following the drought faced in previous years.
This increasing water-supply uncertainty strengthens demand for onsite wastewater recovery and reuse across major semiconductor clusters. Higher recovery requirements translate into investment in RO, UF, membrane treatment, advanced wastewater treatment, monitoring, and closed-loop recovery systems. As drought conditions recur, water recovery increasingly becomes part of core industrial infrastructure planning rather than a temporary response to individual water shortages.
Recent Trends
Taiwan Semiconductor Fabs Integrate AI-Enabled Water Recovery and Advanced Wastewater Treatment
Taiwan’s semiconductor industry is increasingly combining advanced wastewater treatment with higher wastewater-reuse targets, stricter contaminant controls, and increasing treatment complexity are making conventional RO-based recovery insufficient for some process streams. Semiconductor wastewater contains difficult contaminants such as fluoride and other chemicals that require specialized treatment before reuse or discharge. At the same time, fabs need higher recovery rates to reduce dependence on freshwater and manage concentrated wastewater streams. These requirements are increasing the need for advanced membranes, PFAS treatment, ZLD/MLD, real-time monitoring, and automated process control.
The shift is visible in company activity during 2025–2026. At SEMICON Taiwan 2025, Gradiant presented ZLD/MLD systems with recovery rates of up to 99%, its SmartOps AI platform for treatment optimization, and ForeverGone technology for PFAS destruction in semiconductor applications. In Taiwan, ASE operates a 30,000-ton/day middle-water recovery system with a 75% recovery rate and uses AI to predict UF pressure differences, optimize backwashing, and identify wastewater abnormalities. The company reported a 60% reduction in response time through the system.
Taiwan Water Recovery Systems Market Opportunities and Challenges
Semiconductor Wastewater Complexity Creates Demand for Advanced Recovery and Digital Monitoring
Semiconductor wastewater contains contaminants such as fluoride that are difficult and costly to treat and recover, particularly at low concentrations. Taiwan’s National Science and Technology Council highlighted fluoride wastewater as a specific treatment challenge because conventional processes generate additional sludge and recovery limitations. In 2026, researchers developed a membrane capacitive deionization (MCDI) approach to recover low-concentration fluoride wastewater, highlighting the need for specialized treatment technologies. This complexity increases system-design requirements and raises the need for multiple treatment stages, specialized membranes, monitoring, and process optimization.
The treatment challenge creates opportunities for suppliers offering specialized recovery and digital optimization solutions. ASE Technology operates a Kaohsiung water-recycling plant with 30,000 tons/day processing capacity and a 75% recycling rate. By 2025, the company had integrated UF and reverse osmosis systems optimization, automated sludge discharge, AI-predictive membrane cleaning, and AI-based real-time water-quality monitoring into its water-management system. ASE also reported that its Kaohsiung operations had conserved more than 40 million tons of water by April 2025. These applications expand the addressable market beyond conventional treatment equipment into advanced membranes, AI monitoring, automated controls, and performance-optimization services.
Segmentation Insights
Membrane-Based Systems Lead as the Dominant Water Recovery Technology in Taiwan
Membrane-Based Water Recovery Systems account for approximately 42%, supported by their ability to produce high-quality reclaimed water for industrial applications. Their position is supported by extensive use of ultrafiltration and RO in Taiwan’s industrial and municipal reclamation infrastructure. The Water Resources Agency’s Feng Shan project specifies a 45,000 m³/day reclaimed-water plant using pretreatment, UF and RO, while Taiwan’s Taichung Futian facility has tested an SF-UF-RO process for more than three years.
Demand is particularly strong in semiconductor manufacturing. A Taiwan Ministry of Environment case documents a wafer and semiconductor facility using MMF, UF and RO to recover nearly 10,000 tons of water per day, achieving a 50% recovery rate. In Tainan, the Yongkang Water Resource Recovery Center uses MBR as its main treatment process, with part of the MBR effluent further treated through RO for reuse by high-tech companies including TSMC.
These deployments demonstrate that membrane systems are already embedded across Taiwan’s water-recovery infrastructure, particularly where reclaimed water requires higher treatment quality for industrial reuse. By technology, the market is further segmented into the following sub-categories:
- Membrane-Based Water Recovery Systems
- Membrane Bioreactor (MBR) Systems
- Biological Water Recovery Systems
- Advanced Treatment & Disinfection Systems
- Adsorption & Ion Exchange Systems
- Conventional & Physical-Chemical Treatment Systems
- Other Water Recovery Technologies
Water Recovery Equipment & Systems Lead Taiwan’s Market with a 55% Share
Supported by continued investment in physical recovery capacity across industrial and semiconductor clusters. In 2025, ASE operated Taiwan’s largest middle-water recovery facility at 30,000 tons/day with a 75% recovery rate, integrating UF and AI-based process optimization.
In 2026, Taiwan’s Ministry of Environment documented a semiconductor manufacturing facility recovering nearly 10,000 tons/day of reclaimed water at a 50% recovery rate through MMF, UF and RO equipment. The Water Resources Agency is also advancing large-scale recovery infrastructure: its Fengshan project specifies a 45,000 CMD system using pretreatment, UF, RO and disinfection, while Kaohsiung’s Qiaotou plant is scheduled to begin operation in 2026 with 35,000 tons/day of reclaimed-water capacity. This equipment-intensive project pipeline supports the 55% share of water recovery equipment & systems within the offering mix. By offering the market is further segmented into the following sub-categories:
- Water Recovery Equipment & Systems
- Engineering, Procurement & Construction (EPC) Services
- Operations & Maintenance (O&M) Services
- Digital Monitoring & Automation Solutions
Taiwan Water Recovery Systems Market Geographical Analysis
The Southern Taiwan Science Park cluster, covering Tainan and Kaohsiung, accounts for approximately 50% of Taiwan’s water recovery systems market, making it the leading regional market. The region’s position is supported by its concentration of advanced semiconductor manufacturing, where large volumes of process water require continuous recovery and reuse. The Southern Taiwan Science Park recorded an output value of approximately USD 69.5 billion in 2024, highlighting the scale of its high-tech manufacturing base.
Tainan represents a major water-recovery demand center. The Anping Reclaimed Water Plant reached 37,500 tonnes/day of reclaimed-water capacity in 2024, supplying high-tech industries through advanced treatment including reverse osmosis. This connects municipal wastewater recovery directly with industrial water demand in the science-park cluster.
Kaohsiung is strengthening the same demand base through continued semiconductor expansion. TSMC began volume production of 2nm chips at Fab 22 in the fourth quarter of 2025, increasing the concentration of advanced-node manufacturing in Southern Taiwan. This supports continued requirements for industrial wastewater recovery, membrane systems, reclaimed-water infrastructure, monitoring and O&M services across the region.
By 2032, Southern Taiwan remains the leading geographic market, with semiconductor expansion and reclaimed-water infrastructure sustaining demand for advanced recovery systems.
Taiwan Water Recovery Systems Market Competitive Landscape
The Taiwan water recovery systems market is moderately concentrated, with the top five players accounting for approximately 40% combined share. Key players include TCI Corporation, ECOVE Environment Corporation, Forest Water Environmental Engineering Co., Ltd., HDEC Corporation, and WaterPark Environment Corp. (Gradiant Group), competing across equipment, EPC, advanced treatment, and water-reclamation services.
Major market players in the Taiwan water recovery systems market
- TCI Corporation
- ECOVE Environment Corporation
- Forest Water Environmental Engineering Co., Ltd.
- HDEC Corporation
- WaterPark Environment Corp. (Gradiant Group)
- Rotek Water Systems / E-Rotek Water Systems Co., Ltd.
- Puricom Water Industrial Corp.
- Taipure
- Ever-Clear Environmental Engineering Corp.
- Forward Water Technologies Co., Ltd.
Taiwan Water Recovery Systems Market News and Recent Developments
2025: HDEC Advanced the USD 143 million Qiaotou Reclaimed Water PlantHDEC Corporation’s Qiaotou reclaimed water plant in Kaohsiung was more than 80% complete in April 2025, targeting January 2026 operations. The facility is designed to supply 30,000 tonnes of reclaimed water daily to TSMC’s Nanzi fab, increasing to 35,000 tonnes per day by 2027. The USD 143 million project strengthens reclaimed-water infrastructure for Southern Taiwan’s semiconductor cluster.
Impact analysis: The project strengthens the market for large-scale water recovery systems by creating a direct industrial outlet for reclaimed water in Kaohsiung. Its dedicated supply to semiconductor manufacturing supports demand for RO, UF, advanced treatment, monitoring, and O&M systems, while the multi-year capacity expansion creates a longer-term procurement pipeline for suppliers with experience in high-purity industrial water recovery.
2026: CTCI Expanded the Southern Taiwan Science Park Reclamation PlantCTCI Corporation expanded the Southern Taiwan Science Park water reclamation plant in April 2026, increasing capacity from 20,000 tonnes per day toward 30,000 tonnes per day. The facility uses biological treatment, fluidized-bed crystallization, ultrafiltration, and reverse osmosis to recover semiconductor wastewater. It operates under a long-term build-own-operate model supporting TSMC’s water requirements in Tainan.
Impact analysis: The expansion strengthens Taiwan’s industrial water-recovery market by increasing dedicated reclaimed-water capacity for semiconductor manufacturing. Moving from 20,000 to 30,000 tonnes/day expands the equipment requirement for biological treatment, crystallization, UF and RO systems. The project also supports recurring demand for process monitoring, membrane maintenance and O&M services, while CTCI’s build-own-operate model demonstrates the viability of long-term private participation in large-scale industrial water recovery.
2026: Water Resources Agency Completed the Daan–Dajia River Interconnection Pipeline.
Taiwan’s Water Resources Agency completed the 16.38-kilometre Daan–Dajia River interconnection pipeline in July 2026, six months ahead of schedule. The USD 0.482 billion project adds 255,000 tonnes per day of transfer capacity between Taichung and Miaoli water systems and strengthens industrial water security in Central Taiwan. The agency plans to integrate reclaimed water with other sources in its longer-term supply strategy.
Impact analysis: The 255,000-tonne/day interconnection strengthens industrial water reliability across Central Taiwan and creates a more resilient supply network for manufacturing clusters. However, its main market impact is indirect: improved freshwater connectivity allows reclaimed water to function as an additional supply source rather than the sole drought-response option. This supports continued investment in water-recovery plants, treatment equipment and centralized reuse infrastructure as manufacturers diversify water sources and reduce dependence on reservoirs.
- Market Segmentation
- Introduction
- Product Definition
- Research Process
- Assumptions
- Executive Summary
- Taiwan Water Recovery Systems Market Policies, Regulations, and Product Standards
- Taiwan Water Recovery Systems Market Trends & Developments
- Taiwan Water Recovery Systems Market Dynamics
- Growth Factors
- Challenges
- Taiwan Water Recovery Systems Market Hotspot & Opportunities
- Taiwan Water Recovery Systems Market Outlook, 2022-2032
- Market Size & Outlook
- By Revenues (USD Million)
- Market Segmentation & Outlook
- By Water Source Type- Market Size & Forecast 2022-2032, USD Million
- Municipal Used Water
- Industrial Wastewater
- Stormwater & Rainwater
- Other Water Sources
- By Offering- Market Size & Forecast 2022-2032, USD Million
- Water Recovery Systems Equipment & System
- Engineering, Procurement & Construction (EPC) Services
- Operations & Maintenance (O&M) Services
- Digital Monitoring & Automation Solutions
- By Technology- Market Size & Forecast 2022-2032, USD Million
- Membrane-Based Water Recovery Systems
- Membrane Bioreactor (MBR) Systems
- Biological Water Recovery Systems
- Advanced Treatment & Disinfection Systems
- Adsorption & Ion Exchange Systems
- Conventional & Physical-Chemical Treatment Systems
- Others
- By System Type- Market Size & Forecast 2022-2032, USD Million
- Centralized Water Reuse Systems
- Decentralized Water Reuse Systems
- By End User- Market Size & Forecast 2022-2032, USD Million
- Municipal Utilities
- Industrial
- Semiconductor & Electronics
- Pharmaceuticals & Life Sciences
- Food & Beverage
- Chemicals & Petrochemicals
- Power Generation
- Other Manufacturing Industries
- Commercial Buildings
- Residential Developments
- Hospitality & Healthcare
- Government & Public Infrastructure
- By region- Market Size & Forecast 2022-2032, USD Million
- Hsinchu
- Tainan
- Taichung
- Kaohsiung
- By Company
- Competition Characteristics
- Market Share & Analysis
- By Water Source Type- Market Size & Forecast 2022-2032, USD Million
- Market Size & Outlook
- Taiwan Municipal Utilities Water Recovery Systems Market Outlook, 2022-2032
- Market Size & Outlook
- By Revenues (USD Million)
- Market Segmentation & Outlook
- By Offering- Market Size & Forecast 2022-2032, USD Million
- By Technology- Market Size & Forecast 2022-2032, USD Million
- By System Type- Market Size & Forecast 2022-2032, USD Million
- By End User- Market Size & Forecast 2022-2032, USD Million
- By region- Market Size & Forecast 2022-2032, USD Million
- Market Size & Outlook
- Taiwan Industrial Water Recovery Systems Market Outlook, 2022-2032
- Market Size & Outlook
- By Revenues (USD Million)
- Market Segmentation & Outlook
- By Offering- Market Size & Forecast 2022-2032, USD Million
- By Technology- Market Size & Forecast 2022-2032, USD Million
- By System Type- Market Size & Forecast 2022-2032, USD Million
- By End User- Market Size & Forecast 2022-2032, USD Million
- By region- Market Size & Forecast 2022-2032, USD Million
- Market Size & Outlook
- Taiwan Stormwater & Rainwater Water Recovery Systems Market Outlook, 2022-2032
- Market Size & Outlook
- By Revenues (USD Million)
- Market Segmentation & Outlook
- By Offering- Market Size & Forecast 2022-2032, USD Million
- By Technology- Market Size & Forecast 2022-2032, USD Million
- By System Type- Market Size & Forecast 2022-2032, USD Million
- By End User- Market Size & Forecast 2022-2032, USD Million
- By region- Market Size & Forecast 2022-2032, USD Million
- Market Size & Outlook
- Taiwan Water Recovery Systems Market Key Strategic Imperatives for Success & Growth
- Competitive Outlook
- Company Profiles
- TCI Corporation
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- ECOVE Environment Corporation
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Forest Water Environmental Engineering Co., Ltd.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- HDEC Corporation
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- WaterPark Environment Corp. (Gradiant Group)
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Rotek Water Systems / E-Rotek Water Systems Co., Ltd.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Puricom Water Industrial Corp.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Taipure
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Ever-Clear Environmental Engineering Corp.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Forward Water Technologies Co., Ltd.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- TCI Corporation
- Company Profiles
- Disclaimer

MarkNtel Advisors follows a robust and iterative research methodology designed to ensure maximum accuracy and minimize deviation in market estimates and forecasts. Our approach combines both bottom-up and top-down techniques to effectively segment and quantify various aspects of the market. A consistent feature across all our research reports is data triangulation, which examines the market from three distinct perspectives to validate findings. Key components of our research process include:
1. Scope & Research Design At the outset, MarkNtel Advisors define the research objectives and formulate pertinent questions. This phase involves determining the type of research—qualitative or quantitative—and designing a methodology that outlines data collection methods, target demographics, and analytical tools. They also establish timelines and budgets to ensure the research aligns with client goals.
2. Sample Selection and Data Collection In this stage, the firm identifies the target audience and determines the appropriate sample size to ensure representativeness. They employ various sampling methods, such as random or stratified sampling, based on the research objectives. Data collection is carried out using tools like surveys, interviews, and observations, ensuring the gathered data is reliable and relevant.
3. Data Analysis and Validation Once data is collected, MarkNtel Advisors undertake a rigorous analysis process. This includes cleaning the data to remove inconsistencies, employing statistical software for quantitative analysis, and thematic analysis for qualitative data. Validation steps are taken to ensure the accuracy and reliability of the findings, minimizing biases and errors.
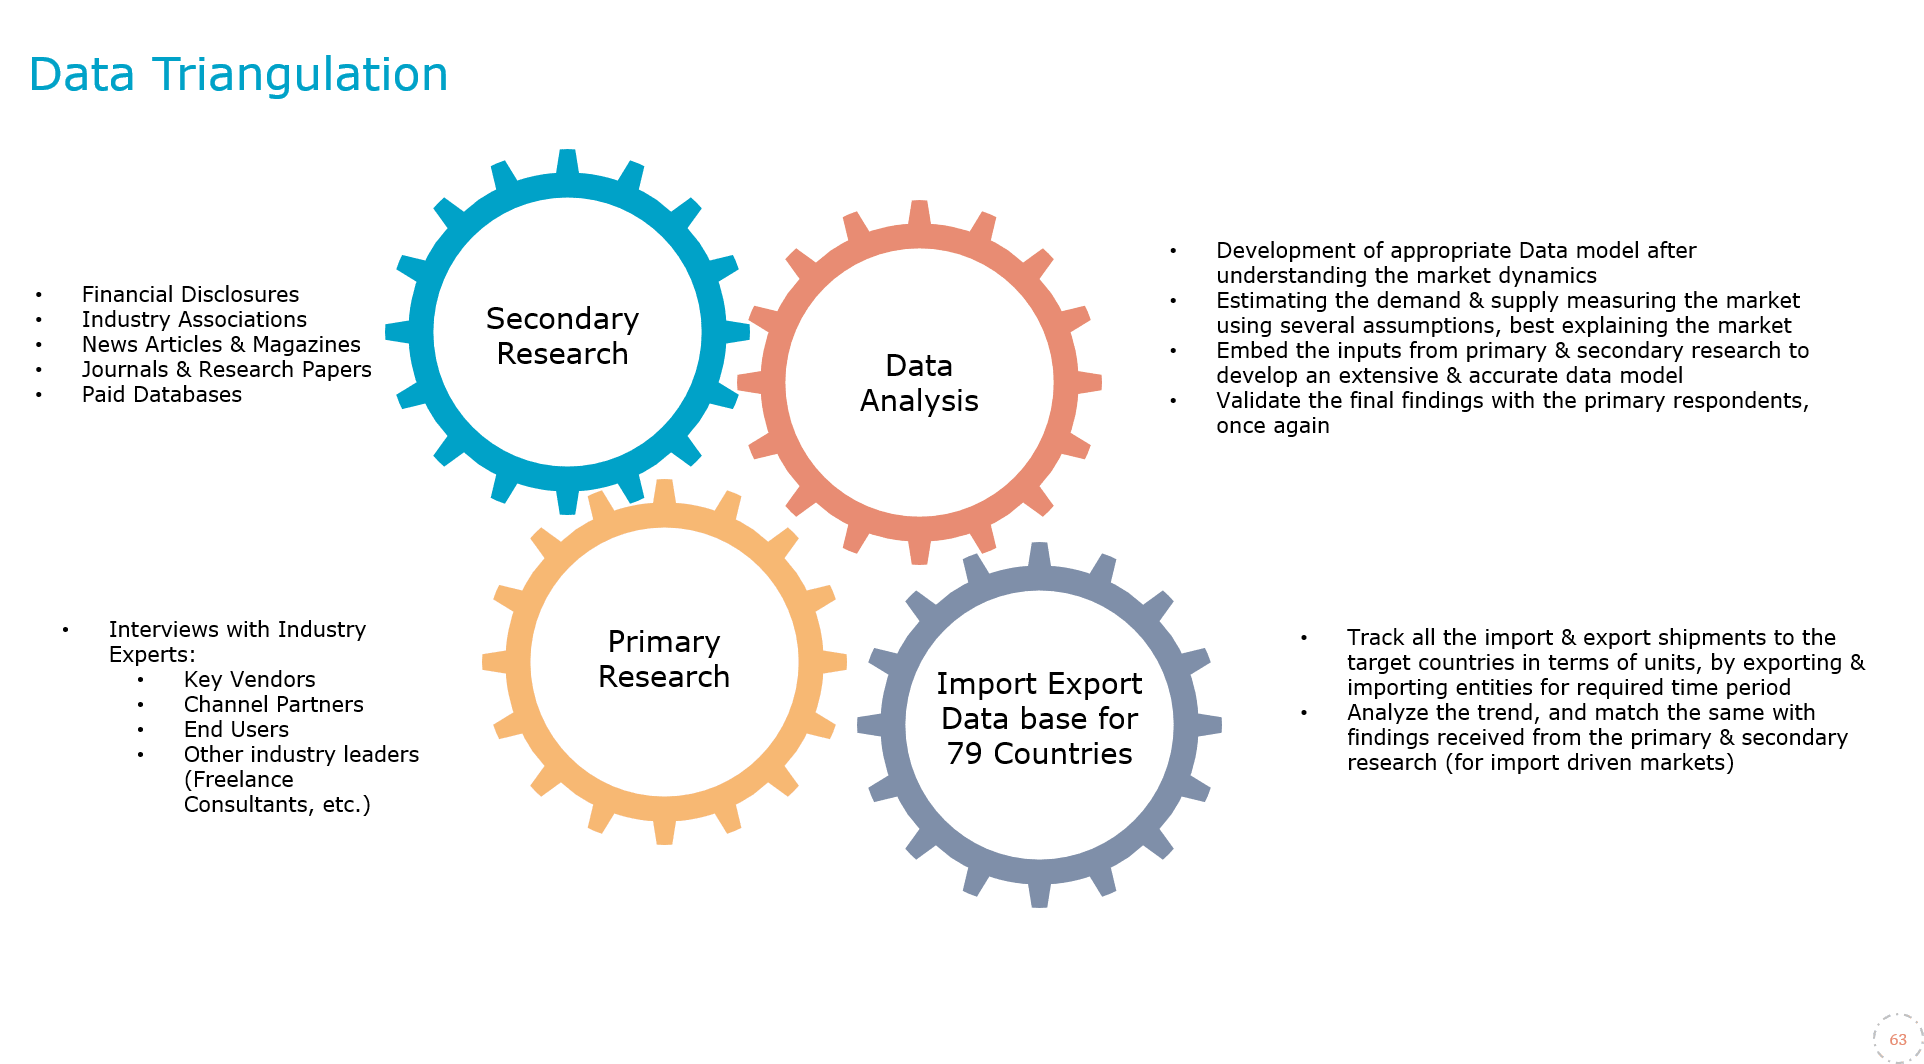
4. Data Forecast and FinalizationThe final phase involves forecasting future market trends based on the analyzed data. MarkNtel Advisors utilize predictive modeling and time series analysis to anticipate market behaviors. The insights are then compiled into comprehensive reports, featuring visual aids like charts and graphs, and include strategic recommendations to inform client decision-making
We’d love to understand what matters most to you.